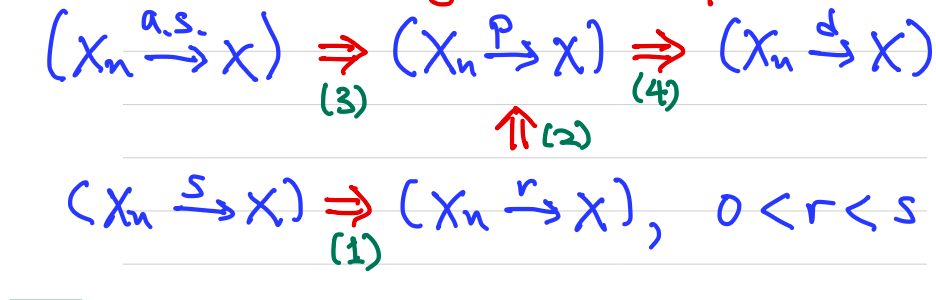Suppose we have , where is very large. We are curious about . What value it converges to? What is its distribution? Law of Large Numbers (LLN) and Central Limit Theorem (CLT) will answer these questions.
Theorem (Weak Law of Large Numbers, WLLN)
Let be a sequence of iid RVs with a finite mean and finite variance . Let . Then ,
I.e. . (see below)
The requirement of finite variance can be neglected, if we consider a stronger version
Theorem (Strong Law of Large Numbers, SLLN)
is a sequence of iid RVs with finite mean . Then
I.e. .
1.2 CLT
Theorem (Central Limit Theorem, CLT)
Again assume . Let . Then
where is the c.d.f of .
I.e. .
The theorem is equivalent to, for large , is well approximated by .
We actually perform a standardization This RV has mean and variance .
Proof
Let . Then . Let . We want to show . So we need continuity theorem of MGF.
Now we want to calculate . Firstly
Apply L'Hospital's rule: So
By continuity theorem of MGF, .
1.2.1 Extensions of CLT
If are independent but not identically distributed, CLT can apply with additional conditions like Lyapunov or Lindeberg condition. A special case is for bounded RVs. Suppose independent, with , , , then if
a constant : .
,
we have
2 Types of Convergence for RV
is an infinite sequence of RVs. is another RV. Assume they are all defined on the same probability space. Of course we can define pointwise convergence
This notion of convergence however, turns out to be too strong.
Almost Sure Convergence
Almost sure convergence, also called strong convergence, convergence with probability , is defined as
Denote as .
More precisely,
I.e., . This is actually a definition for pointwise convergence.
Convergence in Probability
converges in probability if ,
Denote as .
Convergence in th mean
For ,
Denote as .
Convergence in Distribution
Convergence in distribution is also called convergence in law. Here does not need to be defined on the same probability space as . And where .
Denote as .
Equal in distribution does not mean equal in probability. Take a fair coin and toss it twice. Assume the two tosses are independent. . Let be defined as
Then , but . So are not equal in probability.
Example for convergence in distribution: let be RVs with , and . It's easy to see
But this does not affect convergence in distribution, since is not continuous at . (in definition we want )
The three convergence theorems correspond to different convergence.
Almost sure convergence
Convergence in probability
Convergence in distribution
SLLN
CLT
WLLN
3 Convergence Relations
Theorem (Relations between Different Convergence Concepts)
The relations can be shown below:
Proof of (1)
Lemma1
For , any RV satisfies
Proof
Let . This is a convex function since is convex for .
By Jensen's inequality,